Roof insurance claims in Texas: a Benbrook guide
Understand the deductible, depreciation and coverage decisions around a Texas roof claim. Start with the roof’s condition, then keep the work and insurance payment clear.
Understand the work and the payment separately
A roof claim can involve two numbers that sound similar: the cost of the roofing work and the amount the policy pays. Deductibles, depreciation and coverage limits can keep them from being the same.
The explanation below follows Texas Department of Insurance consumer guidance. Use it to read the payment terms, understand your contribution and discuss the roofing work with a clearer view of the budget. The insurer determines coverage under your policy.
Roof condition and insurance coverage are separate questions
Replacement cost and actual cash value pay differently
Illustrative payment example only, not a roof price or claim estimate: assume a covered replacement amount of $20,000, depreciation of $5,000 and a $2,000 deductible.
Policies and settlements vary. See the Texas Department of Insurance roof guide for official explanations of ACV and replacement-cost coverage.
The roofing work and the claim move together
Understand the roof concern
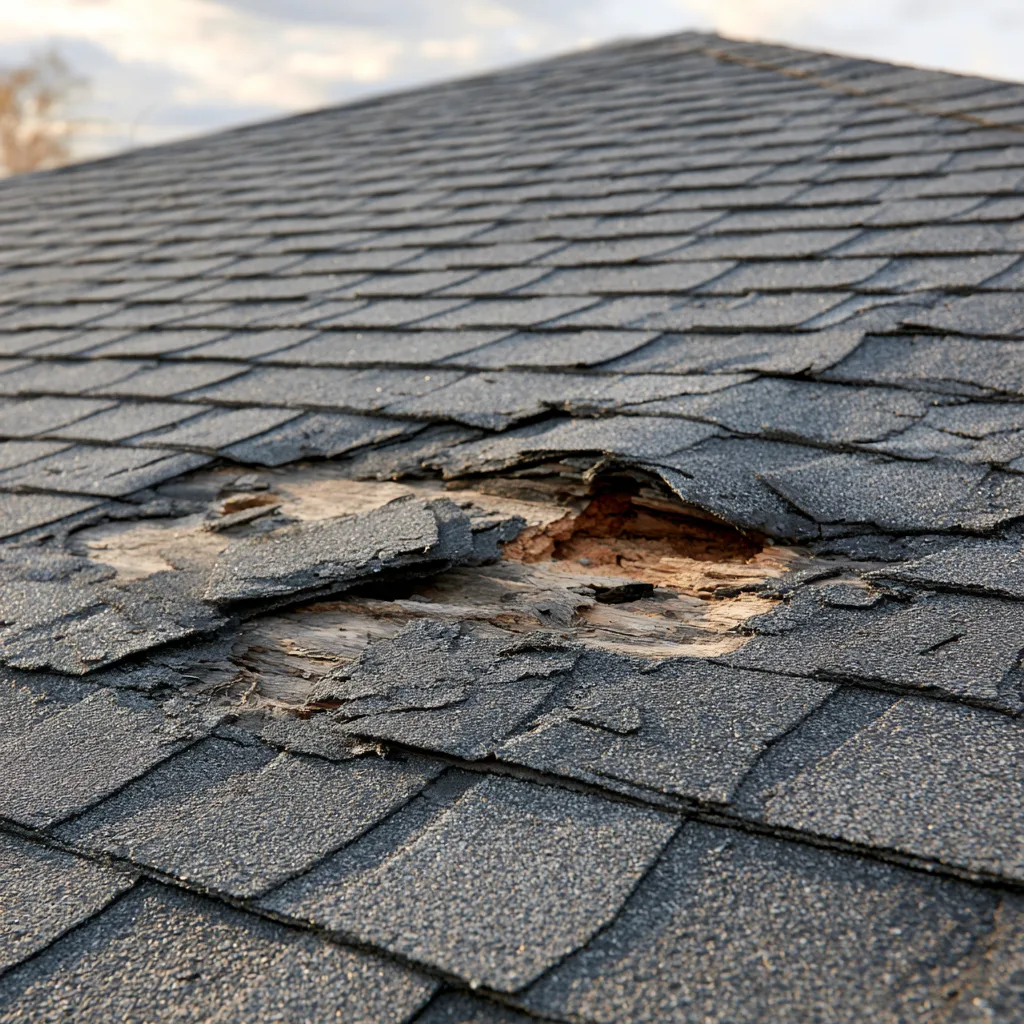
The physical condition needs an examination. A roofing recommendation is not an insurer’s coverage decision.
Follow the policy’s claim process
If you report a loss, the insurer evaluates it under the policy. Dates, cause, exclusions and the deductible matter.
Reconcile work and payment
The roofing scope and insurer’s covered scope may not be identical. Any unresolved difference should be understood before it is treated as funded work.
Meet applicable completion terms
Replacement-cost policies can have deadlines and conditions for recovering depreciation. The policy and insurer determine what proof and timing apply.
The deductible remains your responsibility
- Texas prohibits contractors from waiving, rebating or absorbing an insurance deductible. TDI explains the deductible rule.
- A contractor doing the repair cannot also act as the public adjuster on that same claim. TDI’s roofing and insurance guidance explains the role boundary.
- A promise that insurance will pay for an entire roof does not establish coverage. The policy and claim decision govern the payment.
Texas Roof Insurance FAQs
Does insurance cover an old roof?
Age affects some policy terms and payment methods, but age alone does not answer every claim. Wear and maintenance issues are treated differently from a covered sudden loss. The policy controls.
Does a free inspection require me to file a claim?
No. You can request an inspection to understand the roofing condition without first deciding to report an insurance loss.
How long do I have to finish the work?
Claim reporting, repair and depreciation-recovery deadlines can differ. The insurer and policy should establish the applicable dates; this guide does not substitute one general deadline for them.
Will impact-rated shingles reduce my premium?
Some insurers offer discounts for qualifying products or installations, but a discount is not automatic. See shingle types and impact ratings for the product distinction, then confirm the policy-specific treatment.
Find out what work the roof needs
You can begin with a roofing question. Tell us about the condition at your property and request a free inspection.